If you want to preserve family wealth, the priority is aligning three things: your will, your Vorsorgeauftrag, and your beneficiary designations. Then make sure there’s enough liquidity on hand to cover any tax due when assets pass to the next generation. That’s the whole game, in one sentence.
Do these three things this week:
- Inventory what you own — accounts, property, pensions, insurance, business shares — in one document.
- Confirm your pension and insurance beneficiaries are actually up to date (most people never check).
- Draft or update a Vorsorgeauftrag so a court, not a stranger, isn’t deciding who manages your affairs if you’re incapacitated.
There’s added urgency here. The 2023 reform cut the compulsory portion for children to significantly less than before, which means older wills may no longer reflect the current legal allowances for what you can leave to a partner, charity, or business successor. Marmot Finance works with families across Switzerland to get these pieces working together, not fighting each other.
Key Takeaways
A sound wealth preservation plan coordinates your will, Vorsorgeauftrag and beneficiary designations first, then layers structures and tax timing on top.
What wealth preservation planning actually covers
A proper plan isn’t just a will. It’s a set of coordinated pieces: your will, possibly an inheritance contract (Erbvertrag), a Vorsorgeauftrag for incapacity, correctly filled beneficiary forms on pensions and insurance, any structures you use for a business or larger estate, a rough tax model, and a plan for liquidity so nobody has to sell the family home to pay a tax bill.
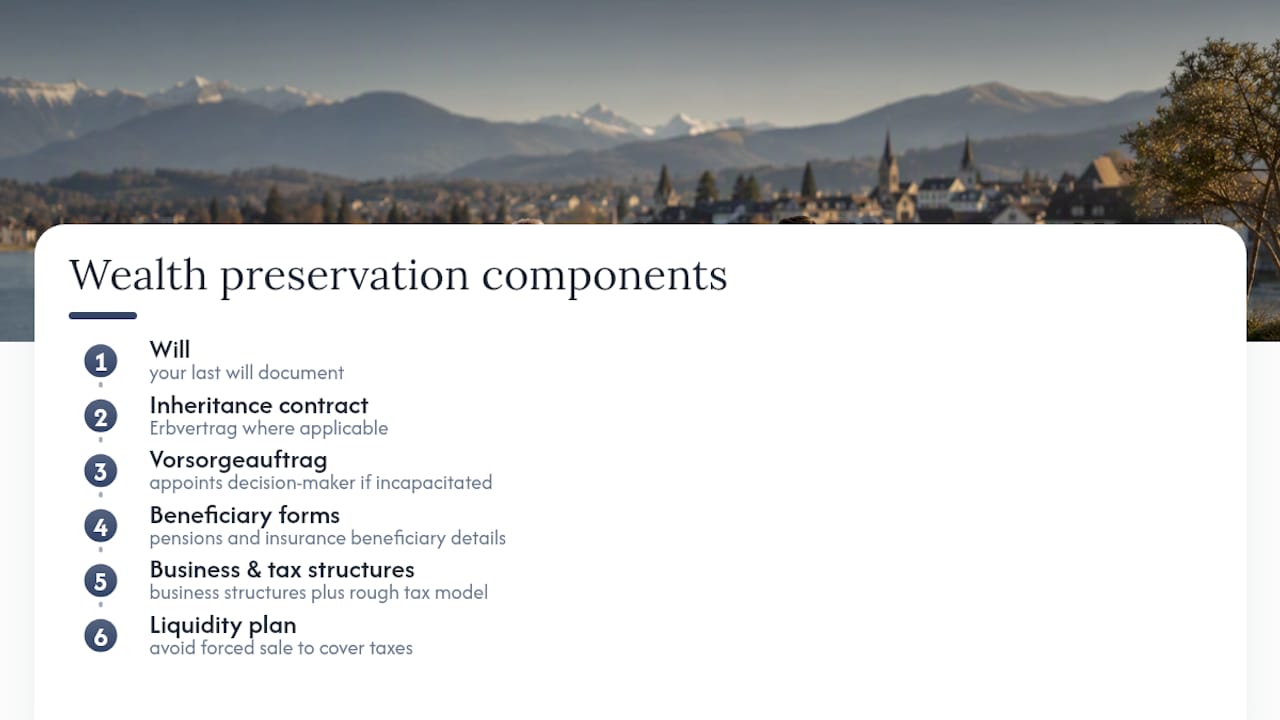
Skip any of these and the gaps show up at the worst possible time. Without a Vorsorgeauftrag, the KESB (the child and adult protection authority) can appoint a guardian of its own choosing if you lose capacity. Without a liquidity plan, heirs sometimes have to force a sale of property or a business stake just to cover taxes or equalisation payments. Blended families, cross border assets, and business ownership all add complexity that a template will simply can’t handle.
Pro Tip: Pull your last will and any beneficiary forms out of the drawer today. If they’re more than five years old, or predate a marriage, divorce, or business sale, they need a second look before anything else on this list.
The core legal instruments: will, Erbvertrag, and Vorsorgeauftrag
These three documents do different jobs, and understanding which one solves which problem saves a lot of confusion later.
- The will (Testament). For many people, a simple handwritten will under Art. 505 ZGB, dated and signed by hand, is enough. It lets you use the freely disposable quota, which increased following the recent reform, to direct more of your estate where you want it.
- The inheritance contract (Erbvertrag). This is the tool for binding arrangements, particularly business succession or a deal between heirs that a plain will can’t guarantee. It requires notarisation under Art. 494 ff. ZGB, which makes it harder to challenge but also harder to change later.
- The Vorsorgeauftrag. Governed by Art. 360 ff. ZGB, this document names who handles your finances and personal affairs if you can’t. Without one, the KESB steps in and appoints someone, and that someone might not be who you’d have chosen.
None of these work in isolation. A will that contradicts your pension beneficiary form, for instance, creates confusion precisely when your family needs clarity most.
Do foundations, trusts, or holding companies actually help?
Sometimes, but not for the reasons most people assume. These structures are governance tools, not tax escape routes, and treating them as the latter usually backfires.
- A Swiss family foundation has a restricted purpose. It can’t simply hand out living expenses like a family bank, and if an endowment eats into a compulsory reserved share, it can face abatement later.
- Foreign trusts are recognised in Switzerland under the Hague Trust Convention; however, Swiss tax authorities typically look through trusts, taxing revocable trusts to the settlor and irrevocable discretionary trusts upon distribution.
- Holding companies with differentiated share classes allow a founder to maintain voting control while transferring economic ownership to heirs or successors.
Practitioners who work with these structures regularly note that founders tend to underestimate abatement risk and cantonal tax exposure, and end up using foundations for continuity and governance rather than as a shortcut around forced heirship.
How cantonal tax rules and timing affect your plan
Wealth tax in Switzerland is a snapshot, not a running total. It’s assessed on what you hold on 31 December, which opens a genuinely useful, entirely legal window each year.
- Make second pillar buy backs or Pillar 3a contributions before year end. Money inside these vehicles typically sits outside your taxable wealth during accumulation.
- Time large invoices or payments to fall either side of the valuation date if it shifts your position meaningfully.
- Remember inheritance and gift tax rules are set cantonally, so where you’re domiciled can change the bill substantially.
- Lifetime gifts can be subject to clawback if they touch a compulsory share, so stagger larger gifts and keep records.
Pro Tip: If you’re weighing a move between cantons, model both outcomes with a tax adviser before you sign anything. The gap between cantons on inheritance tax can be the difference between a modest bill and a painful one.
Getting business succession right
Owner-managed businesses need their own plan, separate from the family estate documents, because the risks are different: a forced sale, a stalled company, or a fight between heirs who never wanted to run it together.
- Get the valuation right first. Circular 28 guidance from the Swiss Tax Conference allows minority discounts in certain cases, and getting this wrong distorts everything downstream.
- Choose your mechanism. Inheritance agreements, usufructs, and staggered share transfers each hand over control at a different pace, so pick one that matches how ready your successor actually is.
- Plan liquidity separately. Taxes and equalisation payments to heirs not involved in the business need cash that doesn’t come from selling company assets.
- Put governance on paper. A shareholder agreement and a family council process head off disputes before they start.
Life insurance, beneficiaries, and the limits of protection
Life insurance and private placement life insurance (PPLI) are underused tools that can deliver liquidity and a degree of creditor protection that a simple bank account can’t.
- A direct beneficiary designation on a life policy usually pays out fast, without going through probate.
- Pension and third pillar designations also sit outside your estate, which means they need to be coordinated with your will, not left to chance.
- Build in a cash reserve for mortgages, business loans, or other illiquid holdings that can’t be sold quickly if money’s needed urgently.
- No insurance structure can lawfully override a compulsory reserved share. It’s a liquidity and protection tool, not a way around forced heirship.
Your 90-day starter checklist
Spread out over a year, this is manageable. Crammed into a weekend, it isn’t. Here’s a realistic order of operations.
- This week: build your asset inventory, confirm every pension and insurance beneficiary, and draft or update your Vorsorgeauftrag.
- Within a month: book a notary and a tax adviser, and request formal beneficiary statements from your pension fund and insurers.
- Within three months: model your cantonal tax exposure, weigh whether a structure genuinely helps your situation, and put governance documents in place if a business is involved.
- Ongoing: revisit the whole plan whenever your family situation, residency, or asset mix changes materially.
Pro Tip: Keep one folder, physical or digital, with every document listed above and a note of who holds the originals. Families lose more time hunting for paperwork than negotiating over it.
Involve the right people at each stage: a wealth manager such as Marmot Finance to coordinate the financial picture, a notary or attorney for the legal documents, a tax adviser for the cantonal modelling, and a trustee or fiduciary if a structure is genuinely warranted.
Why Marmot Finance works with families on this
Marmot Finance is a FINMA accredited wealth manager built specifically for women and families across Switzerland and Europe, managing CHF, EUR and USD accounts. That focus matters when the conversation touches estate planning, because the financial and legal sides need to talk to each other, not sit in separate silos.
- The Money Makeover Quiz gives a starting picture of where your finances actually stand before any bigger decisions get made.
- Financial coaching and educational resources help clients understand the reasoning behind a recommendation, not just follow instructions.
- Over 350 women have already worked through their financial situations with Marmot’s guidance.
- An initial planning meeting typically covers your assets, family structure, and existing documents, then maps where legal and tax specialists need to get involved.
What most advice on this topic gets wrong
Most wealth preservation content treats structures as the headline act: trusts, foundations, holding companies, discussed as if they’re the clever move that solves everything. In practice, the paperwork matters more than the structure. A missing Vorsorgeauftrag causes more real damage, more often, than the absence of a fancy foundation ever will.
The other thing conventional advice underplays is timing. People treat estate planning as a single event, something you do once at 60 and file away. But wealth tax resets every 31 December, forced heirship rules just changed in 2023, and family circumstances shift constantly through marriage, divorce, and business sales. A plan that isn’t reviewed is quietly going stale the whole time you’re not looking at it.
If you take one thing from this article, prioritise the boring documents first. Confirm your beneficiaries, get a Vorsorgeauftrag in place, and only then start asking whether a structure adds anything. Structures are governance tools for people who already have the fundamentals sorted, not a substitute for sorting them.
Talk to Marmot Finance about your plan
Marmot Finance is the alternative to a generic bank appointment for wealth preservation planning in Meilen: instead of a single meeting and a product pitch, you get a hybrid approach that pairs a personal adviser with digital tools built to track your actual financial picture over time, not just at the point of sale.
That matters here because estate and tax coordination isn’t a one-off task. It needs revisiting as cantonal rules, family circumstances, and your own asset base change. Marmot’s wealth management service is built around exactly that kind of ongoing coordination between your investment strategy, your tax position, and the legal documents that protect your family.
If you’re ready to see where your own plan stands, start with Marmot’s wealth management team in Meilen and book an initial conversation.
Sources
Recommended
- Wealth Management in Meilen
- Long-term wealth planning in Switzerland: securing generational wealth
- Preserving Generational Wealth: Private Wealth Management in Switzerland | Marmot Finance
- Tax Optimisation For Entrepreneurs in Meilen | Marmot Finance